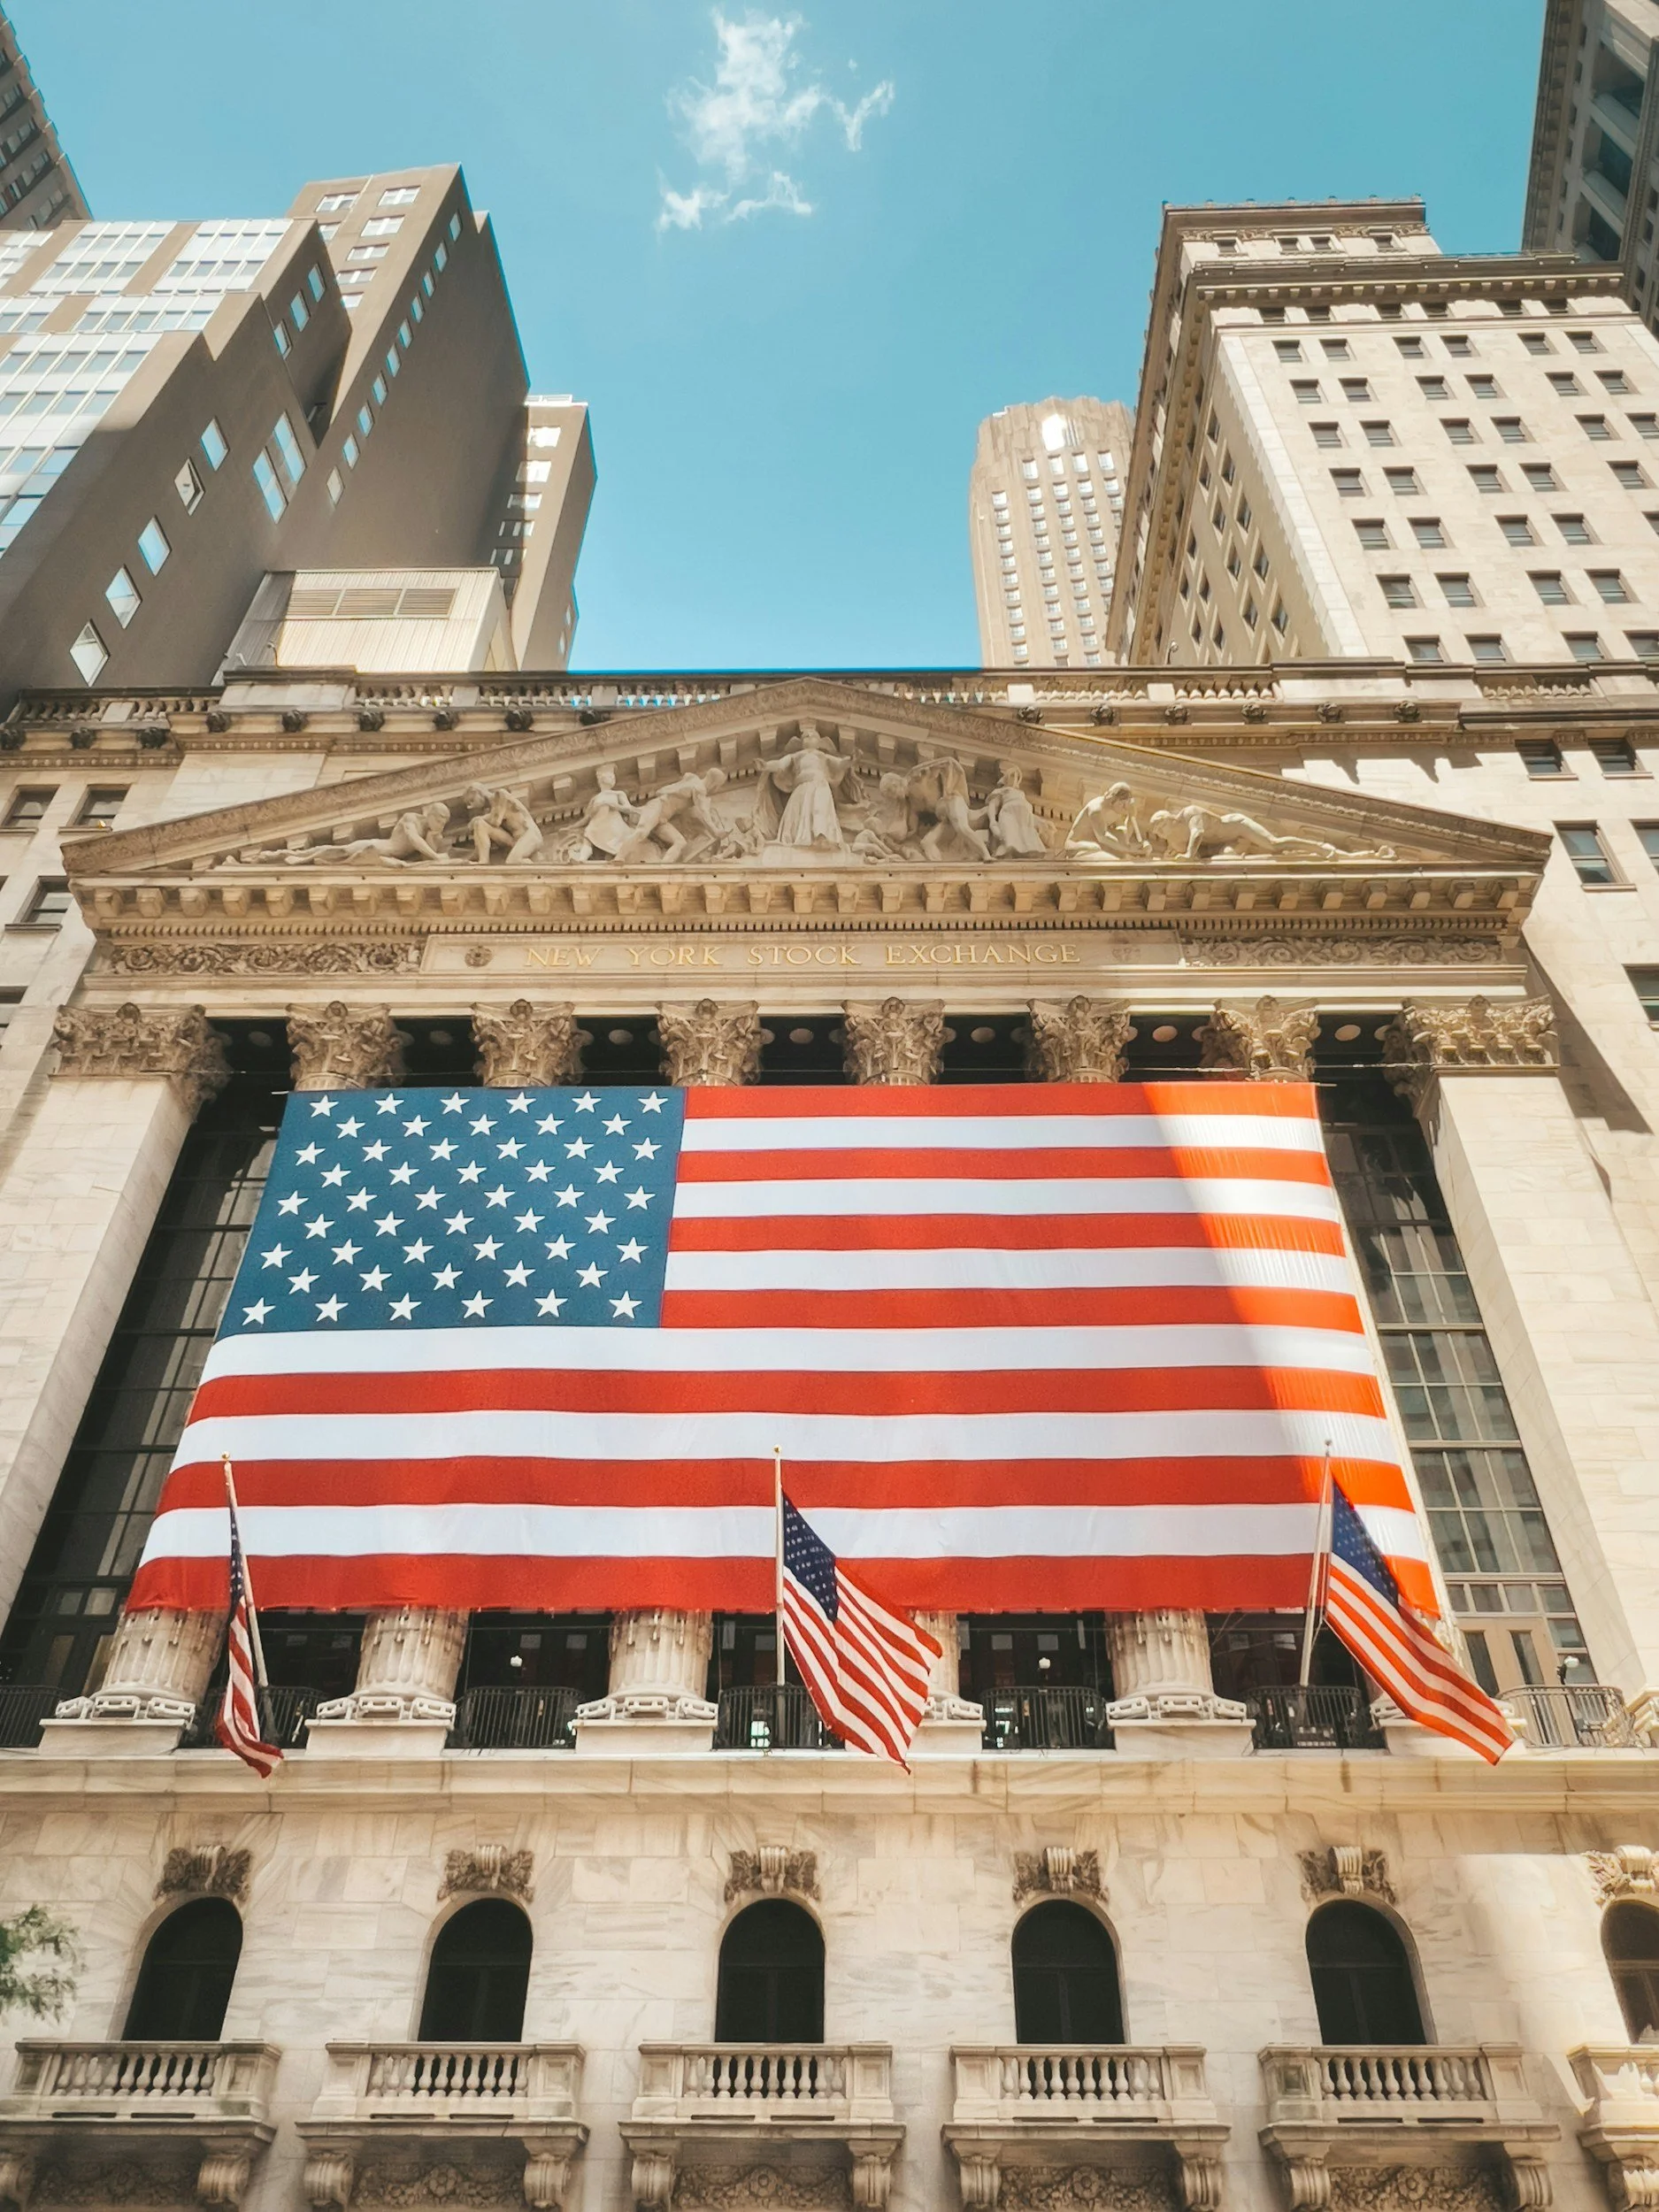
U.S. public equities are worth $68.9 trillion. Gross Domestic Product for 2026 is forecast to be $32.4 trillion. Can you guess which is the tail and which is the dog in terms of importance?
The above numbers are understated. Financial markets overall could be worth much more than that but let’s just count U.S. deposits and money market funds ($20.3 trillion), directly and indirectly held equity shares ($74 trillion), debt securities ($12.2 trillion) and defined pension plan entitlements (16.7 trillion), that amounts to $123.2 trillion.
If you add household and nonprofit sector holdings, that figure is more than $195.9 trillion. Did you know America’s overall wealth jumped by $12.8 trillion in the second quarter of 2026? That was the largest quarterly increase on record. Stock holdings and other financial assets accounted for $11 trillion of that gain.
We can thank the record boom in AI stocks for a lot of those gains. Something else has changed. The wealth effect you may be experiencing has become an important driver of spending and consumption for those of us who hold stocks. But not everyone benefits. The top 1% by wealth hold 51% of stocks and funds, while the bottom 50% hold less than 1%.
Take, for example, higher-income Baby Boomers. They are making net withdrawals from their investment accounts at double the rate they did seven years ago. I know many such couples. They are spending more of their investment gains not only to enjoy life, but in many cases just to pay the bills. Others see their portfolio totals climb year after year, and it makes them feel wealthier, so they spend more.
But it is not only Baby Boomers. A study of 20 million JPMorgan Chase account holders indicates that withdrawals have increased across all ages and income groups. Economic research from Evercore ISI argues that as much as half of all the consumption growth is now being driven by these wealth effects.
Under the current administration, the number of Americans participating in the stock market through retirement savings accounts and now children opening Trump Accounts (60 million) is growing faster than ever before. It is no accident that the president has said many times that he believes the stock market, not the polls, is a better measure of his job standing.
That still leaves a goodly share of low-income households with little if any exposure to the markets. As the brick wall of funding Social Security draws ever closer, I believe that the government will work to convince more Americans to participate in the stock and bond retirement funds through various incentives.
Right now, the U.S. equity market represents 44% of global equity market capitalization. In the second quarter, foreign investors purchased an additional $426 billion of the nearly $1 trillion in overall foreign money flowing into the U.S.
Does this mean that the U.S. stock market has become too big to fail? The short answer is yes.
At this point, equity markets worldwide, both private and public, are well above $200-$300 trillion. That is far greater than the world’s forecasted GDP of $125 trillion. Because the U.S. holds the largest share of that wealth, a large decline in the equity market here would have a debilitating effect on global growth. If the U.S. market falls, global markets will too.
The Financial Crisis of 2008-2009 taught us that the stock market plays a central role in wealth creation, consumer spending, and economic stability. Another prolonged bear market caused by a steep decline in the stock market would surely trigger a recession, high unemployment, and the end of AI investment. I shudder to think of what that would do to consumer confidence.
As such, if such a decline were to happen, I suspect the federal government in this age of state capitalism would intervene, and its actions would dwarf those in past financial crises. I expect a wholesale increase in federal ownership of the stock market (7%- 8%), as well as a huge quantitative easing program numbering in the trillions of dollars.
Bill Schmick is a founding partner of Onota Partners, Inc., in the Berkshires. Bill’s forecasts and opinions are purely his own and do not necessarily represent the views of Onota Partners, Inc. None of his commentary is or should be considered investment advice. Direct your inquiries to his website at www.schmicksretiredinvestor.com. Investments in securities are not insured, protected, or guaranteed and may result in loss of income and/or principal.